Buying your first home in Chicago means navigating a citywide market that behaves very differently block by block. This guide walks through what it actually takes to buy a home in Chicago IL in 2026, from budgeting to closing day. Amy Sunshine works with first-time buyers across the city, and this guide reflects what they need to know right now.
Snapshot: Buying Your First Chicago Home
- The median sale price in Chicago is $420,000, up 6.3% from a year ago
- Homes cost around $303 per square foot, up 5.9% year over year
- Homes are averaging 47 days on the market, with inventory down nearly 29% from last year
- About 42% of homes are selling above asking price, showing real competition for well-priced listings
- Current mortgage rates for buyers are running between 6.4% and 6.9%, depending on the lender and your credit profile
Understanding What You Can Afford Before You Begin
Start by getting a clear, honest number for your budget before you fall in love with a listing. At the citywide median of $420,000, a 20% down payment runs about $84,000, plus closing costs of roughly 2% to 5% on top of that. Get pre-approved early, since a pre-approval letter shows sellers you're serious in a market where 42% of homes are already selling above asking price. Your real number should include your full monthly payment, not just the mortgage, since property taxes and insurance add real cost in Chicago.
Renting vs Buying: Is Now the Right Time to Purchase?
Chicago's rental market has stayed strong, with rents reflecting steady demand for city living. Buying makes sense if you plan to stay several years, since closing costs and moving expenses take time to recover through equity. Chicago's housing market is forecast to see modest, steady growth of 2% to 4% through 2026, rather than a sharp swing in either direction. That steadier outlook means waiting for a dramatic price drop is unlikely to pay off, while buying when you're financially ready remains a reasonable approach.
Exploring the Different Types of Homes Available in Chicago
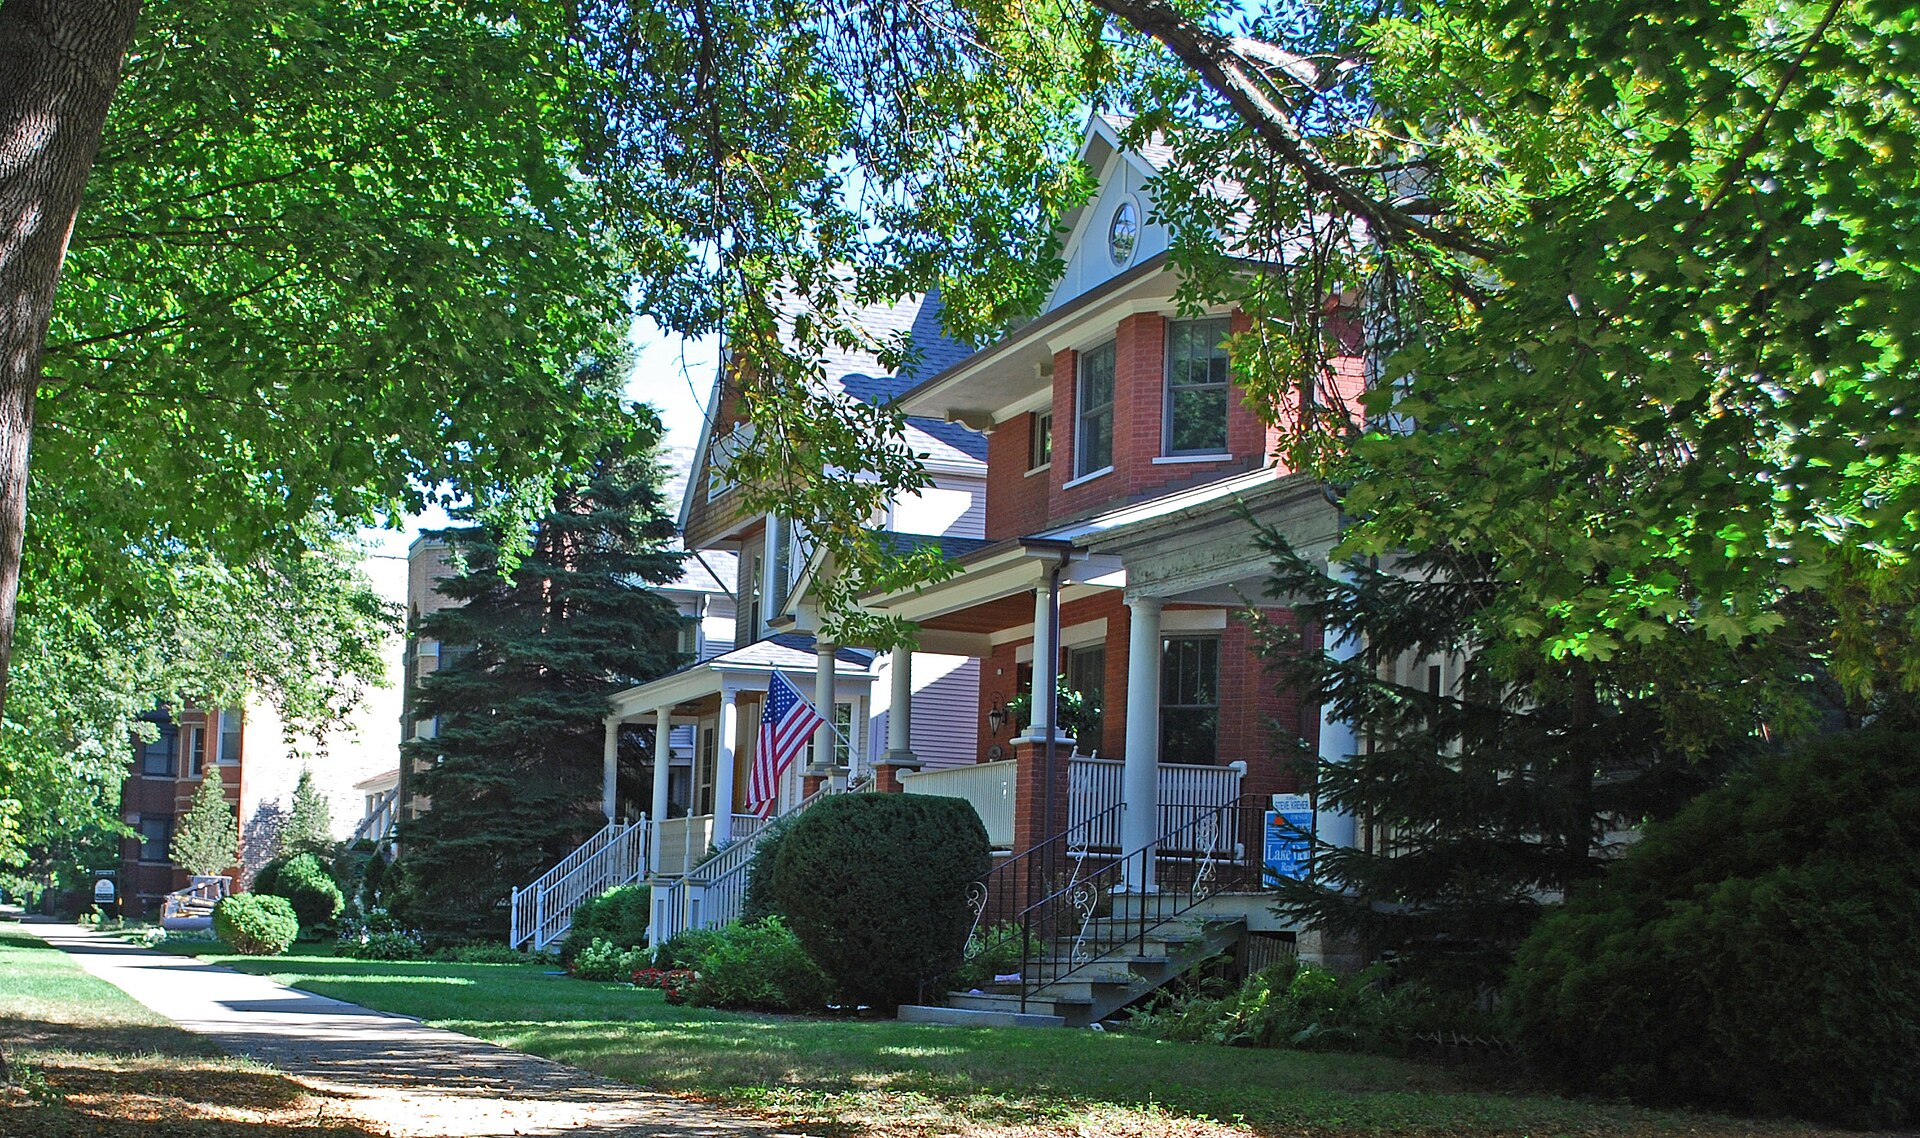
Chicago's housing stock is genuinely varied, from classic two-flats and greystones to modern condos and single-family homes. Downtown and near-downtown areas lean heavily toward condos and high-rises, while many North Side and bungalow-belt neighborhoods offer more traditional single-family housing. Chicago luxury homes for sale tend to cluster in specific pockets like the Gold Coast and Lincoln Park, while more affordable options spread across the South and West Sides. Knowing which housing type fits your lifestyle helps narrow your search before you start touring.
How to Narrow Down Your Home Search Criteria
Write down your real priorities before you start browsing listings. Decide how many bedrooms you truly need, whether parking matters, and how much space you want for the price. Working with a Chicago real estate agent early can help you translate a vague wish list into a realistic, workable search. A focused list also helps you move quickly, since well-priced Chicago homes are currently selling in under 47 days on average.
Choosing a Neighborhood That Matches Your Lifestyle and Budget
Chicago's neighborhoods price very differently, so it pays to compare a few before committing. West Town has recently shown a median sale price of $668,000, up 4.2% year over year, with homes moving in about 45 days. Downtown Chicago runs lower at a median of $430,000, though homes there average a slower 91 days on the market. Buyers researching chicago north side real estate should expect a real range depending on the specific neighborhood, from walkable, transit-heavy areas to quieter, more residential blocks.
Understanding Chicago Home Prices and Market Conditions
Citywide, Chicago's median sale price has climbed to $420,000, a 6.3% increase from a year ago, with price per square foot up 5.9% to $303. Inventory has tightened significantly, down nearly 29% year over year, which has pushed the sale-to-list ratio above 100% in some recent reporting. That combination of rising prices and shrinking supply means first-time buyers should expect real competition, particularly in popular North Side neighborhoods with strong transit access.
What First-Time Buyers Should Know About Property Taxes
Illinois, and Cook County specifically, carries some of the higher property tax rates in the country, with effective rates in Chicago commonly running around 2% to 2.3% of assessed value each year. On a home near the citywide median of $420,000, that typically works out to roughly $8,400 to $9,660 annually before any exemptions. First-time buyers should factor this into their monthly budget alongside the mortgage payment itself, since it can meaningfully affect what you can actually afford.
Looking Beyond the Listing Price: Additional Costs to Consider
Beyond the purchase price, a few costs catch first-time buyers off guard. Closing costs typically run 2% to 5% of the purchase price, covering things like loan origination, title insurance, and attorney fees, which are standard in Illinois real estate transactions. HOA fees apply to most condo purchases and should be reviewed carefully alongside the unit's reserve fund. Homeowners insurance is also worth shopping around for, especially given Chicago's projected increase in extreme heat days over the next few decades. Comparing houses for sale Chicago listings against these full costs, not just the sticker price, gives a much clearer picture of true affordability.
What Makes a Home a Good Long-Term Fit?
A few features tend to hold value well in Chicago's market. Proximity to CTA train lines and strong bus routes supports both daily convenience and long-term resale value. Move-in ready condition matters more now than in past years, since buyers are comparing carefully given tighter inventory. Homes in established, walkable neighborhoods with good school access tend to hold steadier value than properties in areas still building out their identity. Working with a top real estate agent Chicago il buyers trust can help you weigh these factors against your specific budget.
Preparing for Life as a New Homeowner
Once you've closed, budget realistically for ongoing costs beyond your mortgage. Property taxes, homeowners insurance, and routine maintenance all add up, especially in a city with real seasonal weather swings. Setting aside a maintenance fund from day one helps avoid financial stress when something inevitably needs attention. Getting comfortable with your specific neighborhood, from local services to your commute, also takes a little time after closing.
Final Thoughts
Buying your first home in Chicago takes real preparation, given how much prices and pace vary from one neighborhood to the next. Understanding your true budget, including property taxes and closing costs, will help you make a confident offer when the right listing appears. Comparing a few different pockets of the city, from West Town to more affordable South Side options, gives you a realistic sense of what your budget can achieve. Feel free to contact us whenever you're ready to start your search.